

Imagine that ten years ago, you placed RM4 million in Tabung Haji. What would that money be worth today?
There are two ways the story could unfold.
In the first scenario, you leave everything untouched. Every annual profit distribution remains in the account, allowing your money to grow through compounding.
In the second, you withdraw the profit distribution every year and enjoy a six-figure annual income, while keeping the original RM4 million untouched.
Here is the calculation.
Scenario One: Leave Everything In Tabung Haji
Under this scenario, the RM4 million principal and every annual profit distribution remain untouched.
This allows the money to compound because each year’s distribution is calculated on a progressively larger balance.
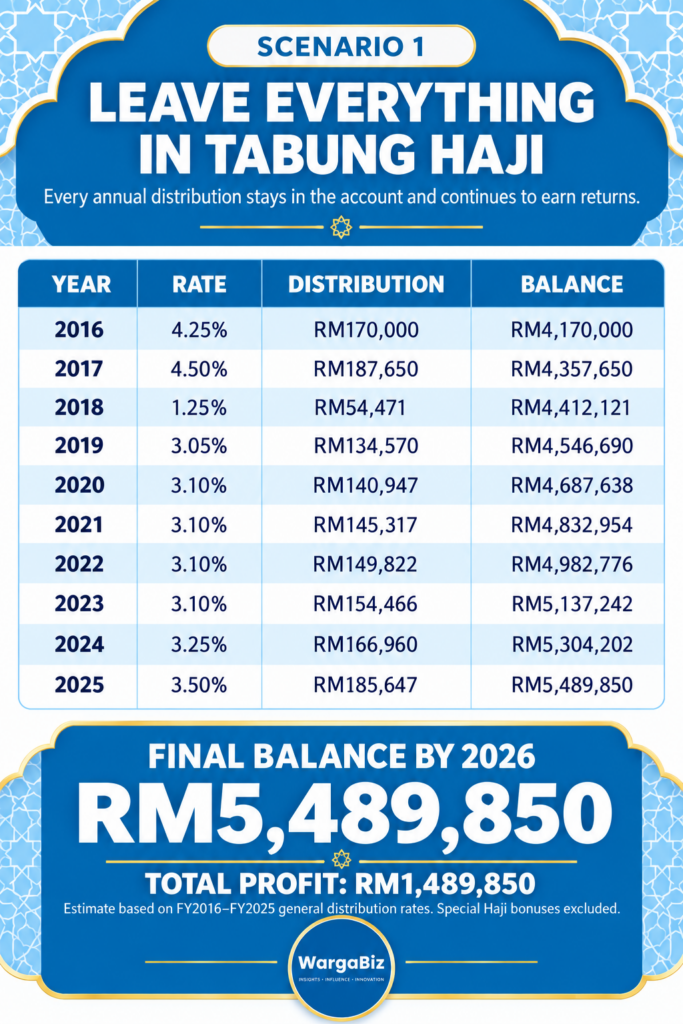
By 2026, the original RM4 million deposit would have grown to approximately RM5.49 million.
Simply by leaving the money untouched, the depositor would have earned almost RM1.49 million in profit over ten completed financial years.
Note: The calculation excludes the additional Hajj Bonus offered in 2016 and 2017. It was available only to eligible depositors who had not performed Hajj and applied only up to a capped average balance.
Scenario Two: Withdraw The Tabung Haji Distribution Every Year
Under the second scenario, the account holder withdraws the entire distribution after it is credited.
Only the original RM4 million remains in Tabung Haji each year. Therefore, there is no compounding effect.
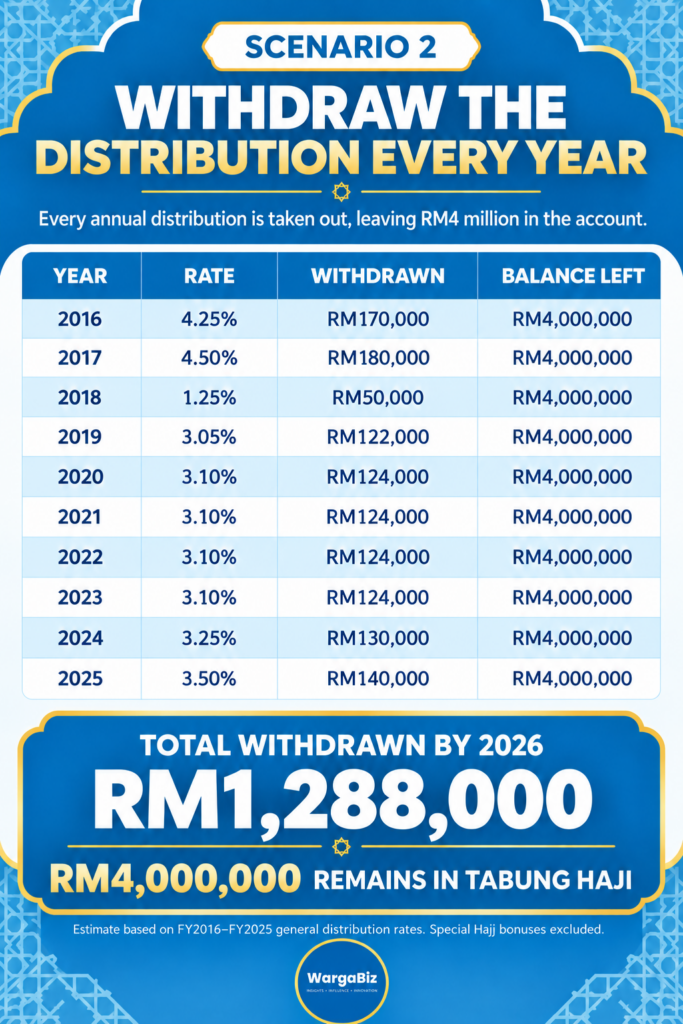
By 2026, the account holder would still have the original RM4 million in Tabung Haji, after withdrawing a total of RM1.288 million in profit distributions over ten years.
This brings the combined value to approximately RM5.288 million, with an average of RM128,800 withdrawn each year. However, the actual amount received would vary depending on the annual distribution rate.
In comparison, leaving every distribution in Tabung Haji and allowing the money to compound would grow the account to approximately RM5.49 million. That is around RM201,850 more than withdrawing the distributions annually.
A Six-Figure Annual Income Without Touching The RM4 Million
The second scenario also shows how much income RM4 million could generate without reducing the original capital.
Depending on the annual rate, the depositor could have withdrawn between RM50,000 and RM180,000 a year.
At the latest declared rate of 3.50%, RM4 million would generate:
RM4,000,000 × 3.50% = RM140,000
That is equivalent to approximately RM11,667 a month, while the original RM4 million remains untouched.
Related articles:
What Really Happened To Tabung Haji? Inside The Nearly RM13 Billion Loss
Did You Know RHB Stands for Rashid Hussain Bank?



Discussion about this post